Wheat imports into the Middle East and North Africa are forecast to fall to 51.1 million metric tons in the July 2026 to June 2027 trade year, according to USDA's November grain report. The projected decline of 14.1 million tons is about 22% from the previous year, a substantial reduction in demand for overseas sellers.
Larger crops change the import requirement
USDA forecasts regional wheat production at a record 73.7 million tons. It points to favorable weather and stronger yields, including larger harvests in Turkey and North Africa. The agency's regional definition includes Turkey as well as the Middle East and North African countries listed in the report.
The import forecast is the lowest since 2012/13. It describes anticipated trade across an entire year, not the volume bought in a new tender or already unloaded at ports. A smaller import requirement can reflect greater domestic availability without implying weaker food consumption.
Fewer tons do not settle the delivered cost
For grain merchants, a smaller regional import market can intensify competition for tenders and shipping business. For millers, additional local wheat can offer an alternative to imported cargoes. Both effects depend on milling quality, location and delivery timing.
A buyer still needs to compare grain specification, freight, insurance, financing and currency costs. Cheaper wheat at an export port does not necessarily mean an equally large fall in the cost delivered to a mill. The distinction complements FOLITIC's coverage of grain prices and uneven export access.
Nor does this forecast establish a reduction in bread prices. Milling, distribution, energy costs and local pricing arrangements stand between a grain purchase and a household transaction. No current retail price change is inferred here.
The forecast still depends on access
USDA also describes constrained Black Sea trade and deferred purchases by some importing countries. That creates two possible paths. Larger local crops could allow buyers to purchase less overseas. If delivery disruptions persist or suitable local milling wheat is insufficient, procurement costs could remain firm even with lower aggregate import volumes.
In the coming week, the US Crop Progress report is scheduled for November 16. It will provide a supply indicator for a competing origin, rather than directly confirm MENA import demand. Subsequent tender awards and shipment data will be needed to test whether the annual trade forecast is materializing.
Sources include USDA's November 2026 Grain World Markets and Trade report, page 6, and the NASS release calendar. The percentage decline is calculated as 14.1 divided by the implied prior total of 65.2 million tons.
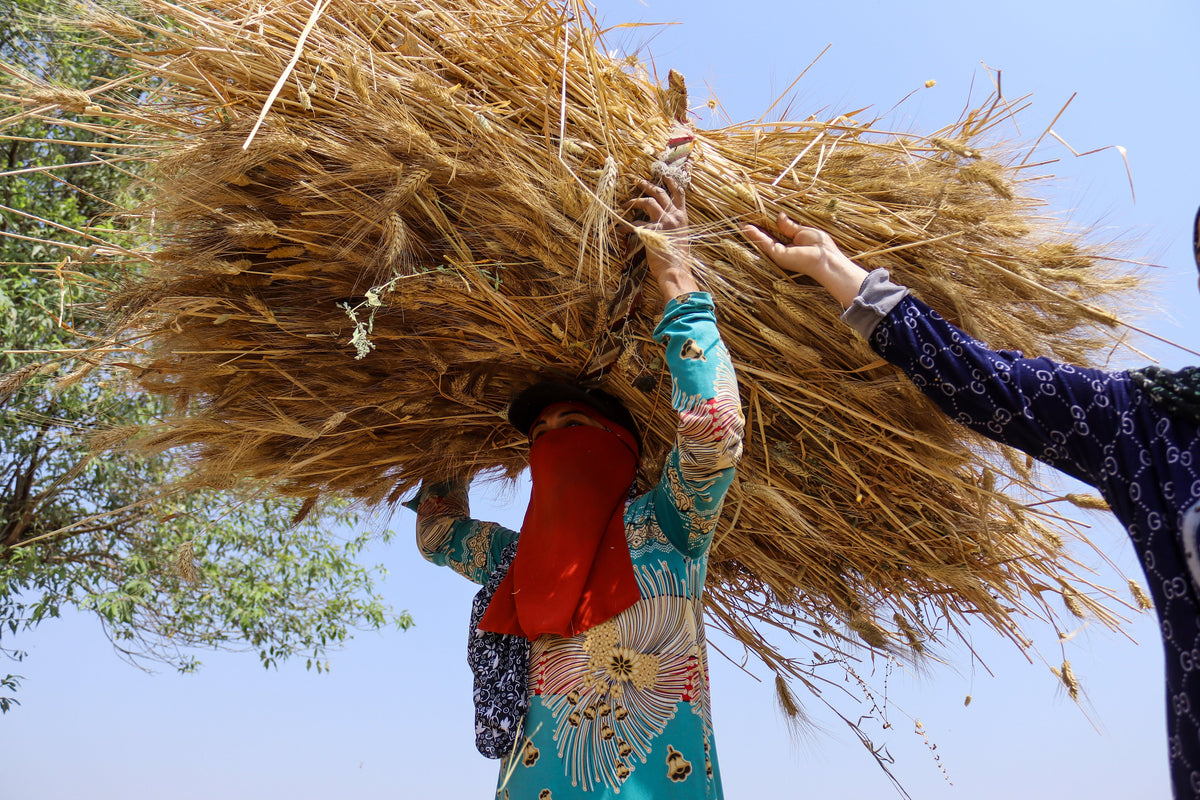
Cover photograph shows wheat harvesting in Sharqia Governorate, Egypt, in May 2024. Photograph by Doaa Adel via Wikimedia Commons, licensed CC BY SA 4.0. Used unchanged as an archival illustration.