China auctioned 1.9 million bales of cotton from government reserves between July and September 2026, according to USDA's November Cotton World Markets and Trade report. The release offered supply to textile mills facing cost pressure, but it does not establish that equivalent import orders have been placed to refill the reserve.
Stored cotton enters the commercial market
Nearly 60% of the auctioned cotton originated in the United States, with the remainder from Brazil and Xinjiang. USDA says the cotton came from crops harvested between 2019 and 2021. Its balance sheets use equivalents of 480 pounds per bale, rather than a count of physical packages of varying weights.
The agency estimates the reserve at roughly 13 million bales, while noting that official reserve holdings and purchases are not publicly disclosed. That is an external estimate, not a published Chinese inventory audit.
Reserve sales and new purchases are separate events
Releasing stored cotton changes availability for mills without creating a new crop. It can reduce the immediate need to source other cotton, depending on fiber quality, auction access and the price paid. A mill must still compare usable fiber costs and financing terms with imported alternatives.
USDA reports industry expectations that the reserve will buy imported cotton to replace sales before the end of the marketing year. This is an expectation, not an announced purchase. Treating it as a completed order would overstate demand for exporters.
If replenishment purchases occur, they could add an official buyer to the market. If they are delayed, exporters cannot assume the auction volume will translate into replacement business on a fixed schedule. These scenarios matter for merchants and spinners with different delivery commitments.
Textile activity is not clothing consumption
USDA forecasts Chinese cotton mill use at 42 million bales for the August 2026 to July 2027 marketing year. Mill use measures fiber processed, rather than clothing sold to households. A change in raw cotton availability does not by itself establish a change in retail garment prices.
The distinction between crop size and industrial demand also appears in FOLITIC's analysis of weaker US cotton mill use. Comparing origins requires consistent bale weights and marketing periods.
The next US Crop Progress report is scheduled for November 16, within the coming week. Harvest progress can inform supply timing for exporters, while any Chinese reserve purchase should be evaluated from a confirmed announcement or subsequent trade data. This article quotes no live cotton or futures price.
Sources include USDA's November cotton report, pages 1, 2 and 5, and the NASS release calendar.
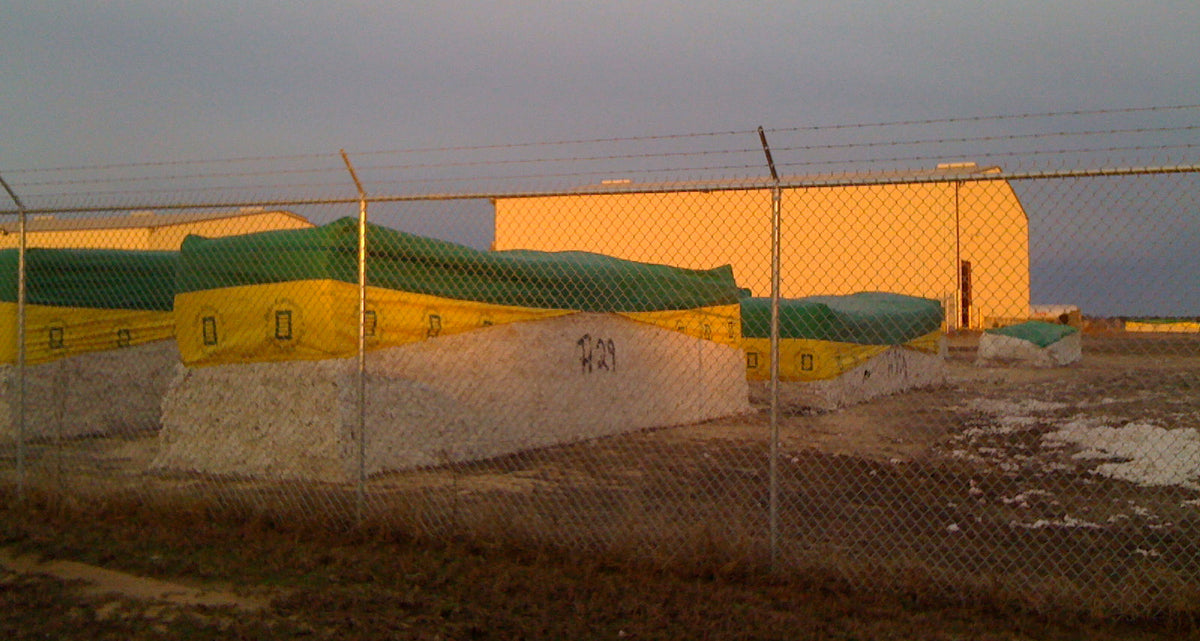
Cover photograph shows harvested cotton modules awaiting processing in North Carolina in October 2010, not Chinese reserve stocks. Photograph by Christopher Ziemnowicz via Wikimedia Commons, licensed CC BY SA 3.0. Used unchanged as an archival supply chain illustration.