Western Union said it delivered notice terminating its agreement to acquire International Money Express after rejecting conditions attached to California regulatory approval. The development shifts attention from integration benefits to what each company can achieve independently.
In its announcement, Western Union, listed on the NYSE as WU, said California delivered final conditions on the evening of November 10. The company argued that these would require material changes to its business model and agent relationships. This is Western Union's characterisation of the conditions, not an independent finding about the regulator.
The company said neither it nor Intermex, listed on Nasdaq as IMXI, must pay the other in connection with termination. An absence of a termination payment does not mean that the abandoned process had no advisory costs or management demands.
The strategic comparison changes
A pending acquisition invites investors to assess a combined business. Termination removes that particular route to combining operations, so expected integration benefits should not remain embedded in an assessment of standalone earnings without another supporting development.
For Western Union, the decision avoids completing a transaction on terms management considers unattractive. Whether that preserves value depends on the alternatives available for investment and the performance of its existing network. Avoiding a deal is not itself evidence of improving customer demand or margins.
For Intermex, the central question returns to independent execution and funding needs. The termination announcement does not establish that another buyer will emerge. An earlier offer price therefore does not establish a valuation floor.
Approvals are conditions, not a vote count
The earlier joint update had already identified California approval as a remaining issue. The episode illustrates that obtaining other approvals cannot substitute for meeting each required closing condition.
The next evidence should come from each company's operating plans and disclosures following termination. Stronger standalone cash generation would support a more constructive assessment. Continued operating pressure would leave the strategic gap unresolved. No verified share price reaction or probability of a replacement transaction is asserted here.
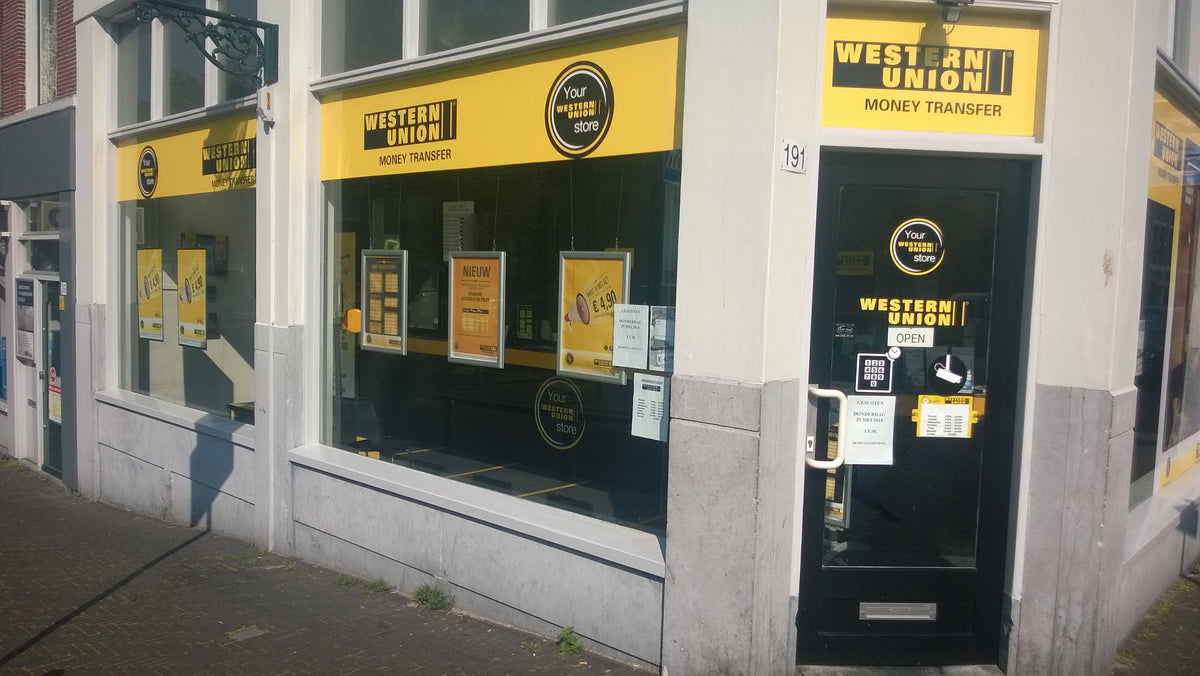
Archival photograph of a Western Union location in The Hague in 2014 by Gijs Bolmeijer, unchanged, under Creative Commons Attribution ShareAlike 4.0.