Research and Risk Practice · REITs
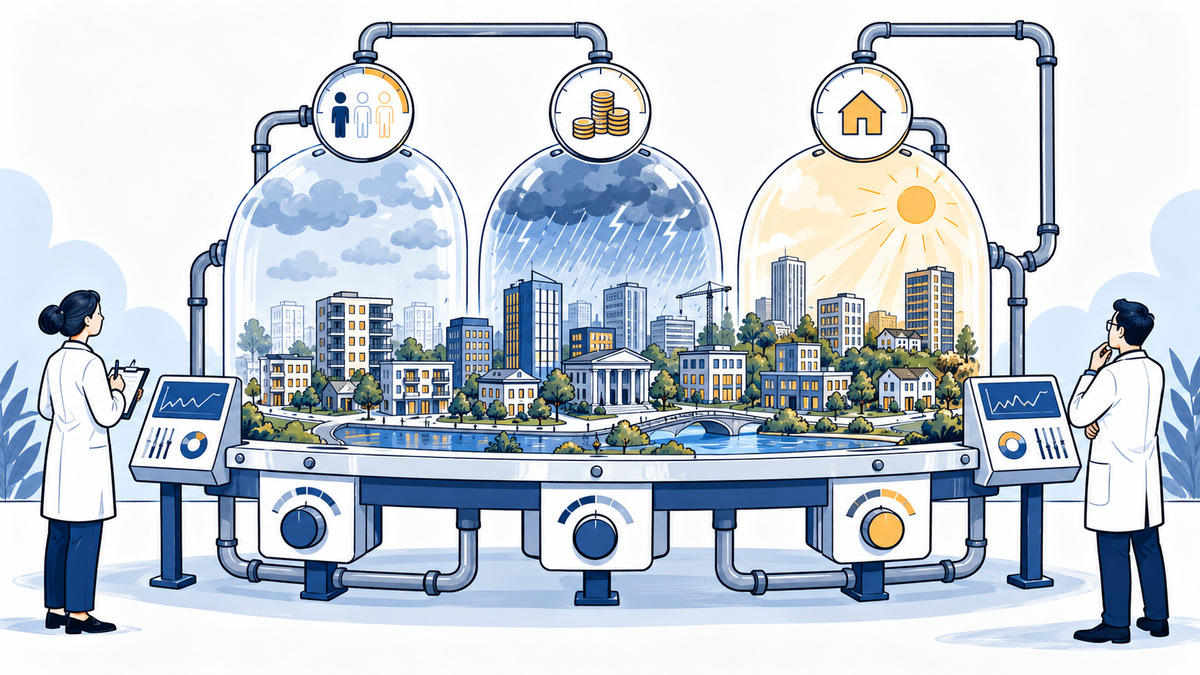
A stress test asks whether the business can withstand several pressures at once. Combine operating weakness, financing changes and valuation effects without counting the same shock twice.
Choose a coherent adverse environment
A recession might weaken rent collection and occupancy while reducing some benchmark interest rates. Funding spreads could still widen. An inflation shock could raise expenses and refinancing costs. Explain the economic story behind the inputs rather than assuming every variable moves independently in the worst direction.
Calculate the operating effect
Start with $50 million revenue and $20 million property expenses, giving $30 million NOI. If revenue falls 10% and expenses rise 5%, NOI becomes $24 million. That is a 20% decline. Relatively fixed expenses can amplify a modest revenue shock.
Carry the effect through financing and valuation
If annual interest also rises from $8 million to $11 million, NOI minus interest falls from $22 million to $13 million before corporate costs and capital spending. For valuation, capitalizing $30 million NOI at 5% gives $600 million property value. Capitalizing stressed $24 million at 6% gives $400 million. With $250 million net debt, simplified equity falls from $350 million to $150 million.
Check survival separately from valuation
A lower estimated NAV does not automatically mean immediate insolvency, and positive NAV does not guarantee enough cash to meet a payment tomorrow. Review debt maturities, covenants, collateral calls and committed liquidity separately. Avoid subtracting the same maintenance requirement twice when it is already included in your chosen cash measure.
Try it yourself
In the example, what is the percentage decline in simplified equity from $350 million to $150 million?
Show the worked answer
The $200 million decline is approximately 57.14% of starting equity. Leverage amplifies the combined operating and valuation shock. This is a scenario, not an expected outcome.
Further reading
Educational material, not a recommendation to transact. All numerical examples are hypothetical and exclude costs unless stated. Actual terms, eligibility, tax treatment and broker procedures depend on the security and jurisdiction.
Continue learning
- Previous lesson: Management incentives and related party transactions
- Next lesson: Turning a REIT earnings report into a research note
- Explore all REITs lessons