

Advanced Research and Risk · Warrants & Rights
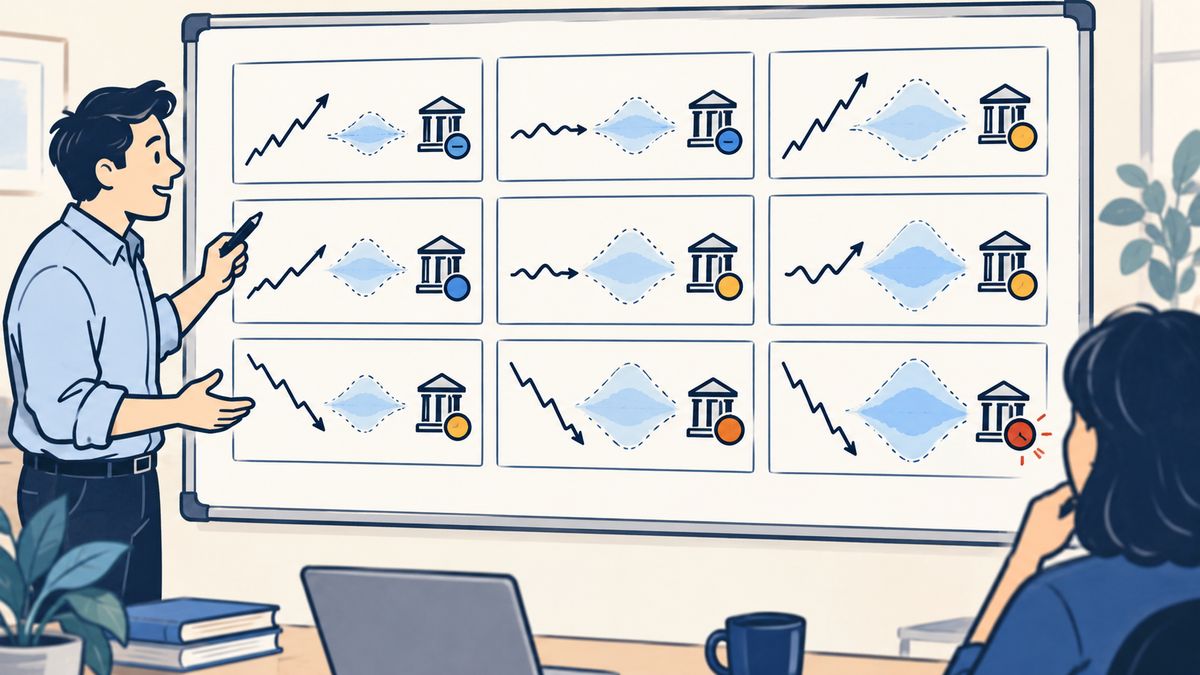
Scenario analysis asks how a position behaves when several assumptions change together. For warrants, price, volatility, time, liquidity and issuer stress should be considered as separate but interacting risks.
Define the valuation date and method
An expiry scenario can often use the contractual payoff formula for a plain warrant. An earlier exit requires a valuation model or a justified market estimate. Label model outputs as estimates and state the inputs. Do not present an assumed exit price as a live quote.
Use more than one market direction
For a hypothetical position of 2,000 warrants bought at $1, consider estimated exit bids of $1.40, $0.65 and $0.10. These produce gains of $800, losses of $700 and losses of $1,800 before costs. Include a zero recovery or worthless expiry case where applicable, which loses the full $2,000 premium.
Each scenario should explain its cause. A favorable share move with lower volatility can differ from the same share move with rising volatility. A delayed move can lose more time value. A wide bid and ask spread can make an estimated midpoint unavailable.
Add operational and credit shocks
Test a trading suspension, an early redemption notice, failed instructions and an issuer stress event. These are not captured by changing the underlying price alone. A portfolio hedged with a put warrant can still suffer if the issuer cannot perform precisely when the hedge is valuable.
For rights, test the share price falling below subscription price, delayed delivery and an inability to sell before the trading window closes. Cash reserved for subscription can also limit other portfolio choices.
Use the results to set decisions
A scenario table is useful when it changes position size, product selection or the decision not to trade. Record which loss is affordable and which assumption would trigger a review. A stop level is a plan, not a guarantee that the market will provide that price.
Try it yourself
A position of 3,000 warrants bought at $0.80 can only be sold at $0.25 in a stress scenario. What is the loss before fees?
Show the worked answer
The loss is $1,650, calculated as 3,000 multiplied by the $0.55 difference. A stop order placed above $0.25 would not guarantee a better result during a gap.
Further reading
Educational material, not a recommendation to transact. All numerical examples are hypothetical and exclude costs unless stated. Actual terms, eligibility, tax treatment and broker procedures depend on the security and jurisdiction.


