Research and Portfolio Decisions · Investment Trusts
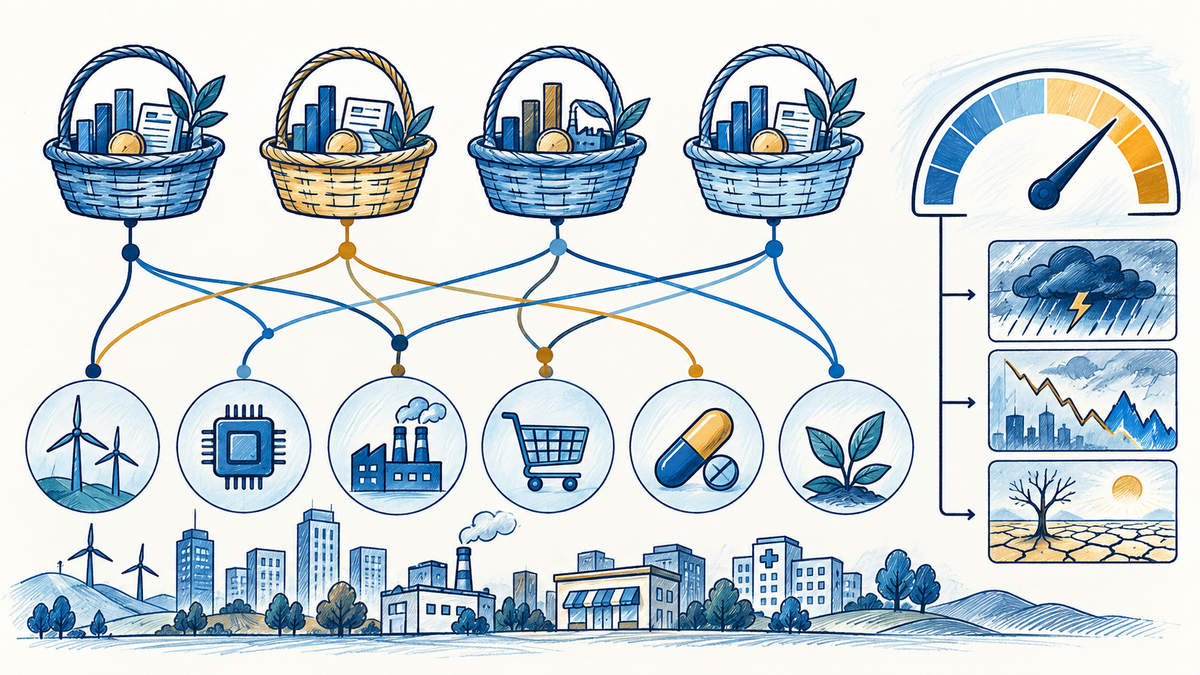
Position sizing connects an individual trust’s risk to the whole portfolio. Overlapping holdings, borrowing and discount exposure can make apparently separate investments move together.
Look through each allocation
Suppose 10% of a portfolio is in Trust A and 15% in Trust B. If each has 20% exposure to the same business, the combined indirect exposure is 2% plus 3%, or 5% of the portfolio, before other holdings.
The overlap can extend beyond individual names. Several trusts may depend on low financing costs, strong technology spending or private asset exits. Different managers do not automatically produce different economic risks.
Stress the share outcome
Start with a hypothetical NAV fall and apply a possible change in discount. Then translate the resulting share loss into the effect on the portfolio. Do not apply a NAV scenario directly to shares while ignoring the entry and exit valuation gap.
If a trust is 7% of the portfolio and its share price loses 30%, the direct contribution is a 2.1% portfolio loss. Correlated holdings may also decline, so this isolated calculation can understate a broader scenario.
Set review rules before emotion intervenes
Define the intended allocation range, liquidity needs and reasons that would justify a change. Rebalancing may involve costs and taxes, so it should not be triggered mechanically by every small movement.
Borrowing inside a trust and borrowing in the investor’s own account can compound exposure. Evaluate the combined position rather than assuming that a small headline allocation is necessarily modest risk.
Try it yourself
You hold 12% in a trust with 25% in one sector and another 8% in a trust with 50% in that sector. What is the indirect sector allocation?
Show the worked answer
It is 3% plus 4%, giving 7% of the portfolio before any other direct or indirect exposure.
Further reading
Educational material, not a recommendation to buy or sell a fund. Numerical examples are hypothetical. This guide focuses on listed investment companies commonly called investment trusts in the UK. Product terms, access and tax treatment vary by jurisdiction.
Continue learning
- Previous lesson: Build a fair investment trust comparison
- Next lesson: Monitor a trust without chasing every price move
- Explore all Investment Trusts lessons