

Research and Trade Management · Futures Trading Guide
A promising historical result is a hypothesis. Testing it on data that did not choose the rules helps reveal how much of the apparent edge may be selection luck.
Separate development from evaluation
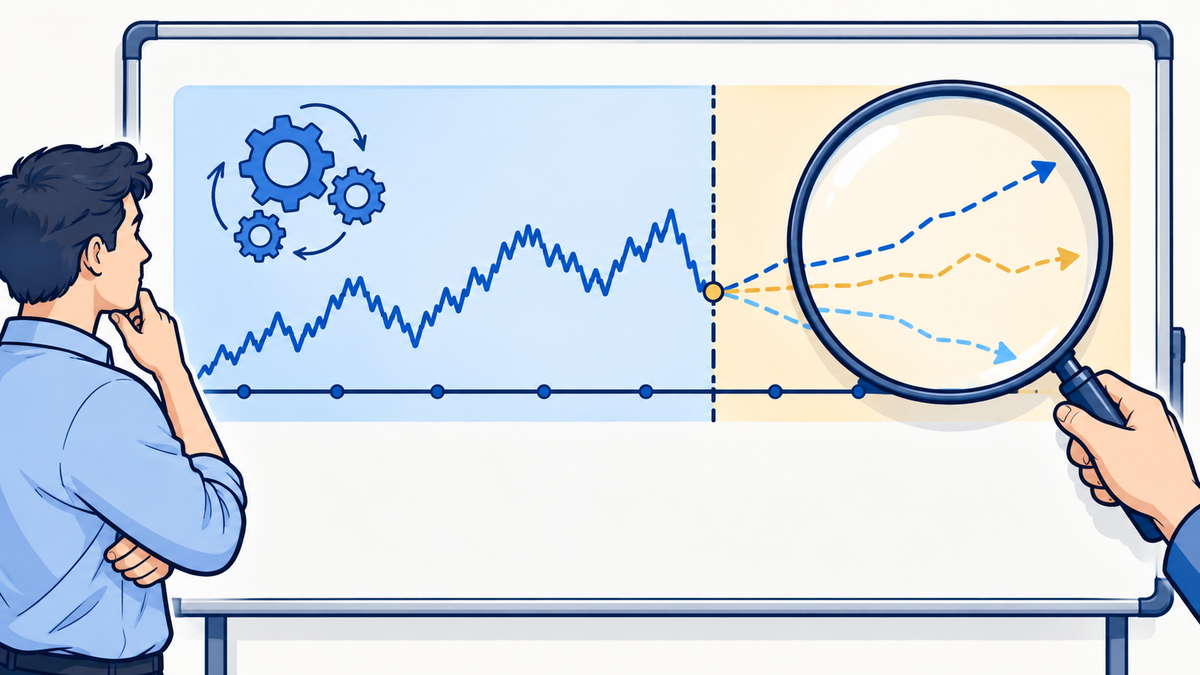
Develop the rule on an initial chronological sample, then freeze it before evaluating a later period. A walk forward process repeats this sequence using only information available before each new evaluation interval. Keep a final untouched sample when feasible. Once that sample influences a modification, it is no longer an independent final test.
Calculate expectancy after costs
Assume a hypothetical method wins 40% of trades, averages $300 on wins and loses $150 on losses. Gross expectancy is 0.40 times $300 minus 0.60 times $150, or $30 per trade. If average costs are $12, estimated net expectancy is $18. These sample averages do not guarantee the next trade or establish statistical confidence.
Count every attempted variant
Searching hundreds of lookbacks, markets and filters increases the chance of finding a strong result by accident. Record unsuccessful variants as well as the selected one. The research literature on backtest overfitting explains why repeated selection can weaken ordinary holdout conclusions. Prefer a clear economic rationale and stable behaviour across reasonable neighbouring assumptions over one isolated optimum.
Test uncertainty and deployment limits
Review confidence ranges, dependence between trades, drawdowns and adverse execution scenarios. A small sample of clustered trades may contain less information than its count suggests. Compare performance across regimes and contracts, then use forward observation or simulation before risking capital. Define what evidence would invalidate the method, including costs that erase its estimated advantage.
Try it yourself
A strategy wins half its trades, earning $120 per win and losing $100 per loss. Average costs are $15. What is estimated net expectancy?
Show the worked answer
Gross expectancy is $10 per trade. After $15 of costs, net expectancy is negative $5. A 50% win rate alone says little about profitability.
Further reading
- Bailey and coauthors: The probability of backtest overfitting
- CME Group: The cost of trading
- CME Group: Futures trade plan
Educational material. Prices, margins and strategy examples are hypothetical unless explicitly identified as contract specifications. They are not trade recommendations. Futures losses can exceed deposited collateral. Product terms and eligibility vary by venue and jurisdiction.


