Reading Futures Markets · Futures Trading Guide
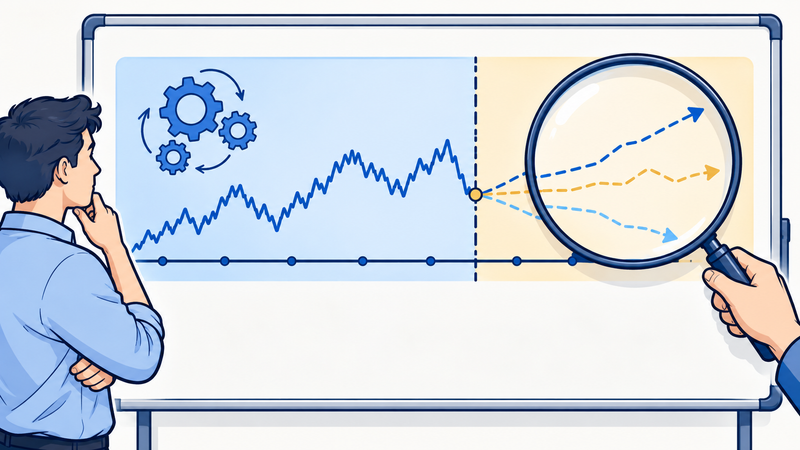
A futures curve compares maturities at one moment. Its shape is different from a chart showing one contract through time.
Put time on the correct axis
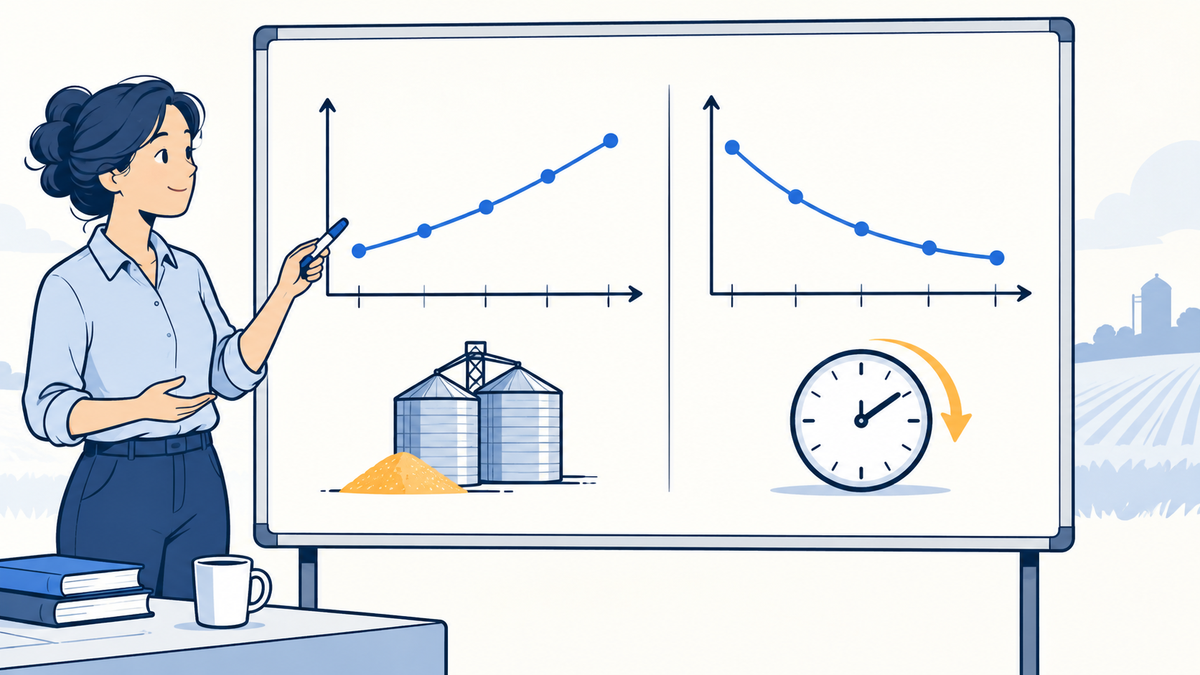
A term structure plots prices for several delivery months observed at the same time. A historical chart plots observations through time. Mixing these views can make an upward curve look like a prediction that the asset must rise. Futures prices incorporate financing, storage, availability and other market forces. They are not an unbiased promise of the future spot price.
Name the shape carefully
Contango commonly describes later contracts priced above nearer exposure or spot. Backwardation describes the opposite relationship. Curves can bend and have mixed sections, so specify the maturities being compared. For storable commodities, financing, insurance and storage can support a premium for deferred delivery. The benefit of having usable inventory now is often discussed as convenience yield.
Compare a simple curve
Suppose fictional oil contracts quote 80 for the nearby month, 82 for the next and 85 for a later month. The next minus nearby spread is 2. If the first two later change to 83 and 84, that spread narrows to 1 even though both outright prices rose. A trade on the spread therefore has a different exposure from a directional oil trade.
Connect the observation to a testable question
Ask whether the move reflects inventory, transport constraints, seasonal demand or financing. Use the same observation time and compatible contract specifications. A curve can change sharply when supply is disrupted, and distant contracts may have weak quotes. For cash settled products, convergence follows the specified reference mechanism. For deliverable commodities, grade and location matter. Do not assume a local physical quote must equal every exchange contract price.
Try it yourself
Nearby futures are 104 and the following maturity is 101. What is the later minus nearby spread, and what shape does this pair show?
Show the worked answer
The spread is negative 3. The nearby contract is more expensive, so this pair is backwardated. That observation alone does not establish the next trade’s return.
Further reading
Educational material. Prices, margins and strategy examples are hypothetical unless explicitly identified as contract specifications. They are not trade recommendations. Futures losses can exceed deposited collateral. Product terms and eligibility vary by venue and jurisdiction.