Spreads and Relative Value · Futures Trading Guide
Relative value across equity indices or interest rate contracts requires a measure of the exposure being matched. Equal contract counts rarely answer that question.
Choose the exposure you intend to neutralise
An equity index pair can be matched by notional value, estimated beta or another risk measure. An interest rate pair is often compared using DV01, the approximate cash change for a one basis point yield move. Neutrality to one measure does not remove all market risk. Sector composition, curve changes and volatility can still drive losses.
Calculate an equity notional match
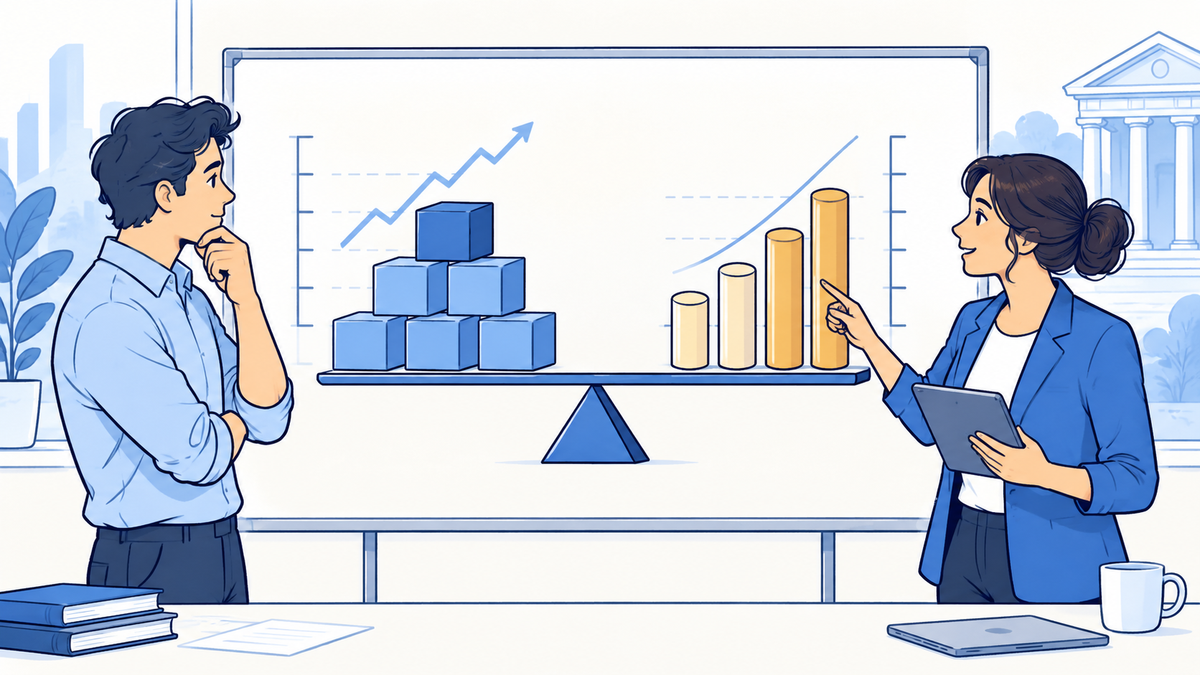
Assume fictional index A trades at 5,000 with a $10 multiplier, creating $50,000 notional per contract. Index B trades at 2,000 with a $25 multiplier, also $50,000. One against one matches notional. If the long A rises 1% and the short B rises 1.5%, the spread loses $250 before costs. Matching notional did not make returns equal.
Match rate sensitivity rather than face value
Suppose contract C has an estimated DV01 of $80 and D has $40. One long C against two short D contracts approximately offsets a small parallel yield move. It remains exposed to different movements at each maturity, convexity, delivery options and changes in the underlying sensitivities. A contract’s face amount alone would not reveal this relationship.
Monitor the assumption that holds the pair together
Record the hedge measure, its source date and rebalancing rule. Test steepening and flattening scenarios, sector shocks and an impaired exit in one leg. Include financing and variation cash demands where relevant. Treat the residual exposure as the actual trade, and do not describe a statistical relationship as a guaranteed convergence opportunity.
Try it yourself
A long position has $240 of DV01. Each potential short hedge has $60 of DV01. What simple parallel sensitivity hedge does this imply?
Show the worked answer
Four short hedge contracts approximately offset $240 of DV01. The estimate does not hedge every curve or basis movement.
Further reading
- CME Group: Hedging with equity index futures
- CME Group: Understanding Treasury futures
- CME Group: Treasury duration adjustment
Educational material. Prices, margins and strategy examples are hypothetical unless explicitly identified as contract specifications. They are not trade recommendations. Futures losses can exceed deposited collateral. Product terms and eligibility vary by venue and jurisdiction.