

Asset Classes and Global Exposure · ETFs
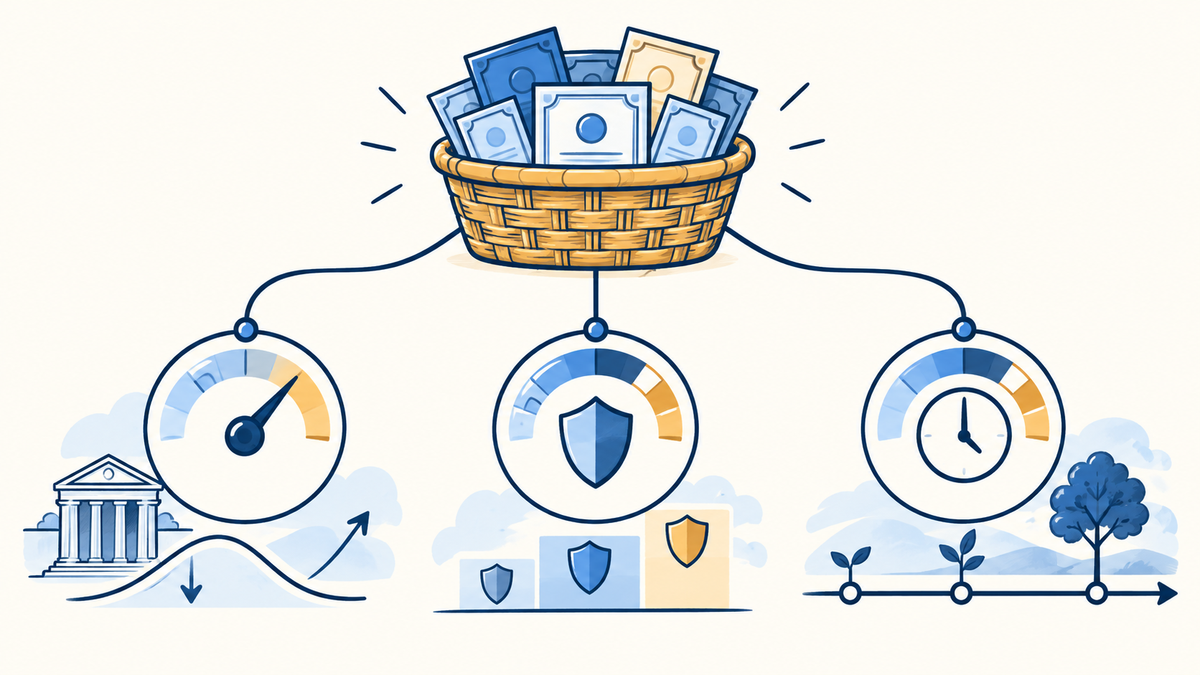
Bond ETFs package interest rate and credit exposures into a tradable portfolio. Their yield, duration and maturity profile answer different questions.
Separate income from price sensitivity
A bond portfolio can pay income while its market value falls. Duration estimates sensitivity to changes in yields. For a small parallel yield increase of one percentage point, a duration of five suggests an approximately 5% price decline before income and other effects. This is an approximation. Convexity, changing spreads, defaults and portfolio turnover can alter the result.
Read credit exposure alongside duration
Government, investment grade corporate and high yield portfolios face different credit and economic risks. A lower duration fund can still suffer from deteriorating credit. Ratings provide useful information but are neither permanent nor guarantees. Examine issuer concentration, sectors and exposure to stressed borrowers as well as the average rating.
Maturity is not always your repayment date
A conventional bond ETF continually maintains an exposure as bonds mature or leave its index. It usually has no single maturity at which your original investment is returned. Defined maturity bond ETFs follow a different lifecycle, but their final distributions still depend on holdings, defaults, expenses and termination arrangements. Review the actual structure rather than importing assumptions from an individual bond.
Use yields carefully
Distribution yield measures past or recent cash payouts under a specified method. Yield to maturity and standardised yield figures use different assumptions. None should be treated as a guaranteed personal return. Suppose you buy at $100, receive $4 and sell at $96. Ignoring costs, your total return is zero despite collecting 4% in cash. Include price changes and the timing of withdrawals when evaluating a bond allocation.
Try it yourself
Two bond ETFs have similar yields. One has duration two and the other eight. Which is approximately more sensitive to a small parallel increase in yields, all else equal?
Show the worked answer
The duration eight fund. A one percentage point increase implies roughly an 8% price decline versus 2%, before income, convexity and other changes.
Further reading
Educational material, not a recommendation to transact. All numerical examples are hypothetical and exclude costs unless stated. Actual terms, eligibility, tax treatment and broker procedures depend on the security and jurisdiction.
Continue learning
- Previous lesson: Equity ETFs sectors countries and concentration
- Next lesson: Commodity ETFs spot exposure futures and roll costs
- Explore all ETFs lessons


