Singapore has opened a new route for sovereign institutions to hold gold, adding custody infrastructure before the next stage of its trading system arrives. For the bullion market, the immediate significance is where metal can be stored and accessed. The announcement does not establish an increase in global gold purchases.
Storage opens before clearing
The Monetary Authority of Singapore announcement on 10 November 2026 describes a service for foreign central banks, international financial institutions and sovereign entities. The national currency vault has capacity for up to 500 tonnes, with potential expansion. Capacity is not a reported deposit balance.
MAS also outlined a broader tax framework for selected wholesale gold services, expected from April 2027. Preparations for the gold clearing system are expected to finish by the end of 2026, with operations anticipated in the first quarter of 2027. A physically deliverable kilobar futures contract is targeted for the second quarter. Those milestones remain prospective.
Allocated custody changes the operational question
The official custody description says specific bars are assigned to customers and recorded individually. Deposited gold must meet LBMA Good Delivery standards. Deposits, withdrawals and transfers are supported, while access to bullion bank services depends on bilateral arrangements.
This matters because storage location, ownership and trading liquidity answer different questions. Moving existing bars to Singapore could change geographical distribution without changing total official gold holdings. A transfer within a custody system need not require fresh mine supply. Treating the full vault capacity as incremental demand would therefore overstate what the release establishes.
The test is usable liquidity
Closer access to counterparties during Asian trading hours could reduce operational friction if sufficient institutions and dealers participate. That would be relevant to bullion banks, refiners and institutional holders arranging settlement. It would not necessarily improve the earnings of every gold miner or make retail gold products equivalent to allocated custody.
A stronger market development case would require evidence of participation, workable settlement arrangements and sustained trading activity. Slow onboarding or shallow liquidity would weaken that case even if storage infrastructure functions as planned. Neither scenario provides a gold price target.
The MAS calendar lists an October assets and liabilities release for 13 November. That is within the coming week, but it should not be presumed to disclose customer deposits under the new service. The operational milestones above fall later.
Readers can compare this distinction with FOLITIC's guide to the limits of positioning data. A measured balance describes a defined population and date. It is not interchangeable with a flow or a forecast. No spot quotation or measured price response is asserted here.
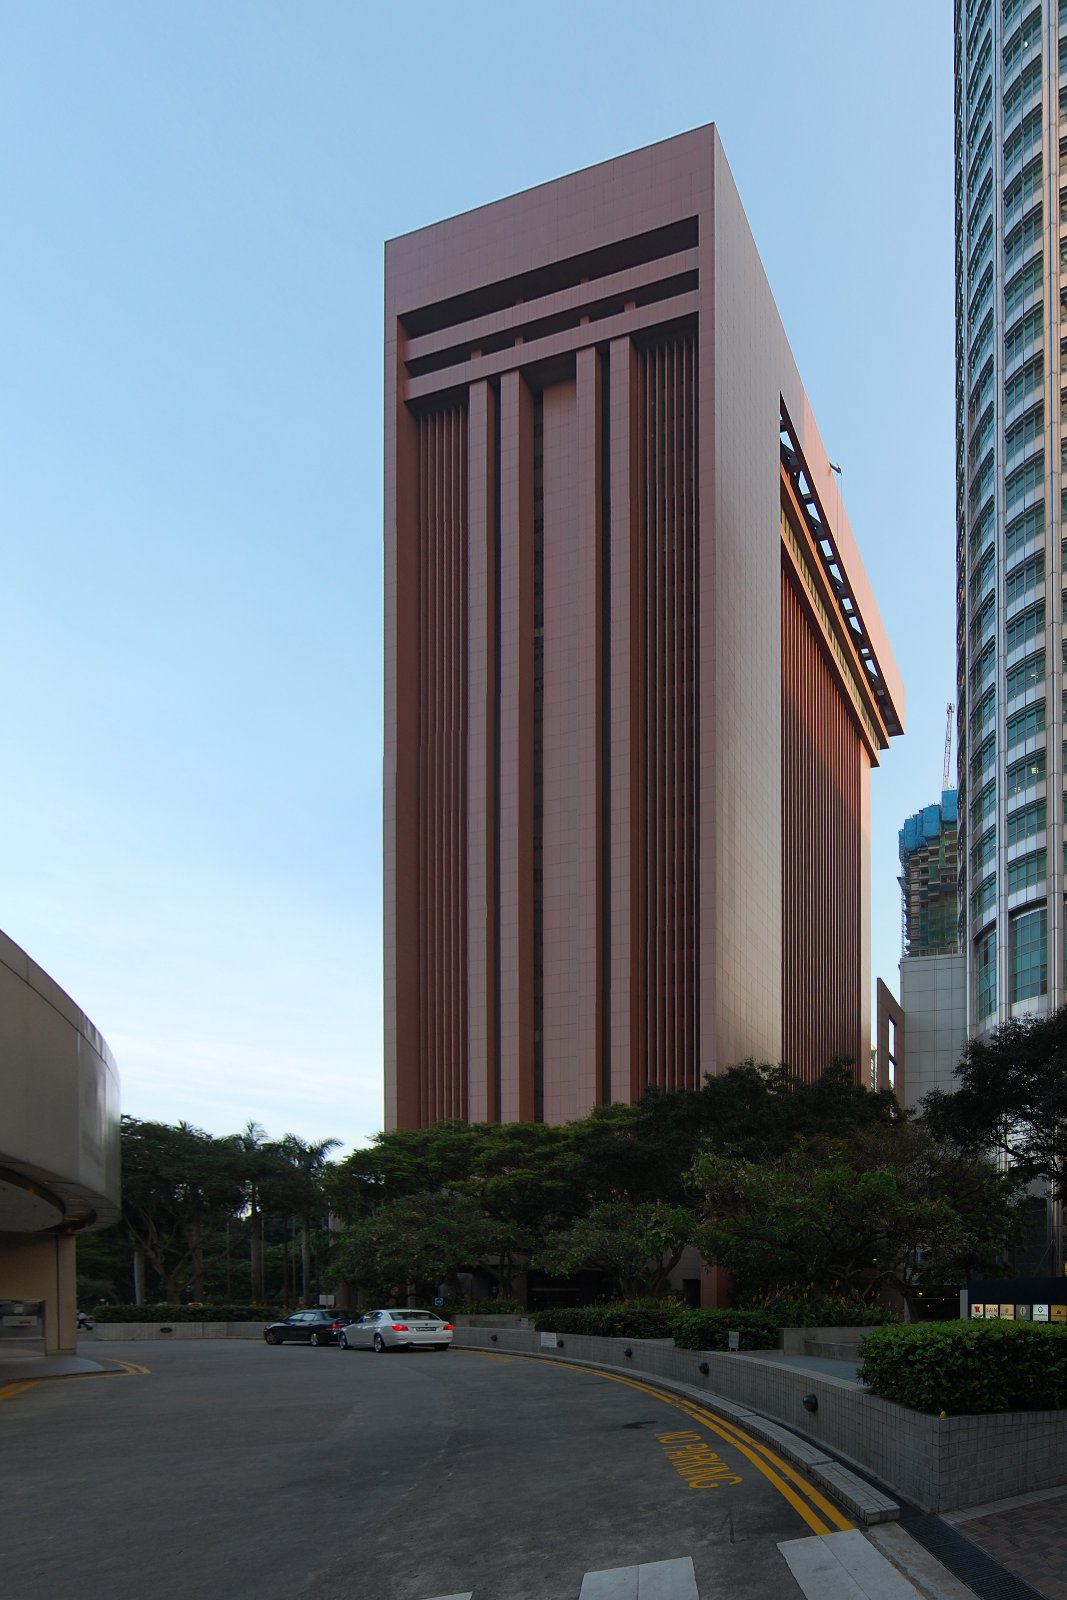
Archival photograph of the MAS Building, 14 September 2009, by Nicolas Lannuzel via Wikimedia Commons. Licensed under Creative Commons Attribution ShareAlike 2.0. Display sizing and preview cropping may apply. The photograph remains under the same license and does not depict the vault or its contents.