

Selection and Ongoing Review · Collective Funds
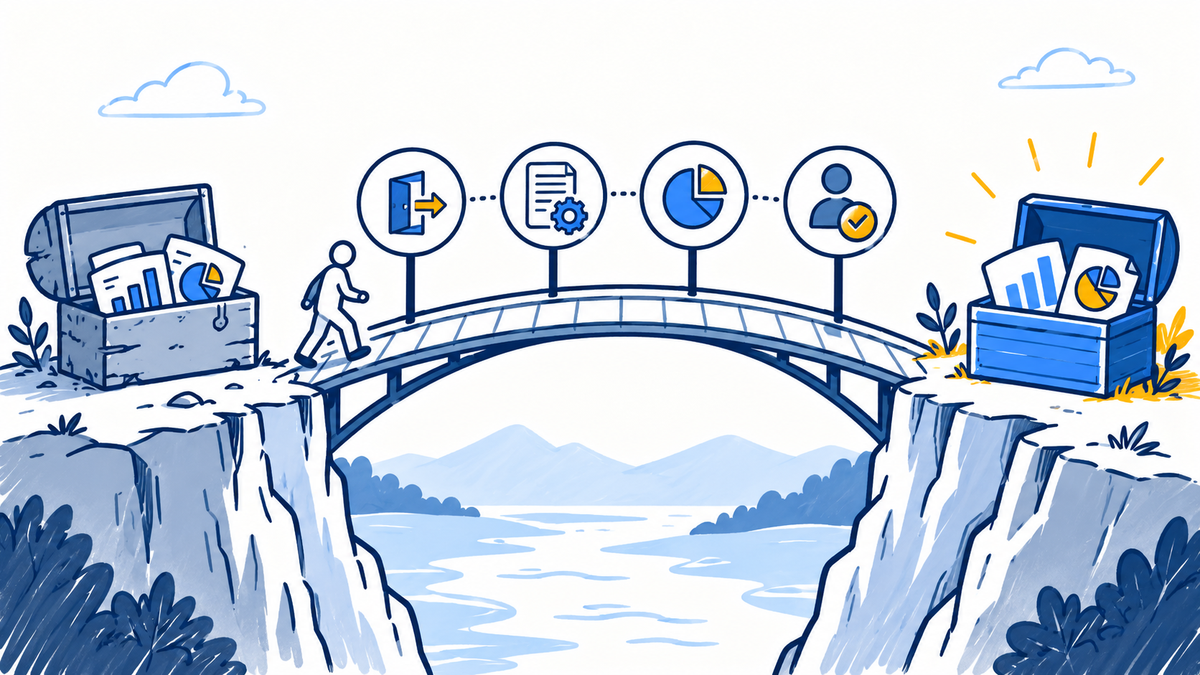
Changing funds involves more than selecting a replacement. The exit and entry processes can create costs, timing gaps and temporary changes in market exposure.
Map both sides of the move
Confirm the current fund’s notice, dealing and settlement terms. Then confirm destination eligibility, class, minimums and entry timetable. A plan level replacement may follow different provisions from an individual participant transfer.
Identify whether the move occurs in cash, through an agreed asset transfer or through another permitted arrangement. Do not assume an asset transfer is available just because the two funds have similar holdings.
Estimate implementation effects
Suppose $100,000 is redeemed and remains uninvested for three days before entering a similar market exposure. If that market rises 2% during the gap, the missed gain is about $2,000 relative to continuous exposure. If the market falls, the cash interval can help instead. Neither outcome is known in advance.
Trading costs, spreads and transition services can also matter. The purpose is to plan and measure the move, not to time a short market fluctuation with confidence.
Confirm and reconcile
Create a sequence of instructions, responsible parties and expected confirmations. Check units removed, proceeds received, charges and units purchased. Preserve records needed for account or tax reporting.
A successful transition is one that follows the intended process with understood costs and risks. The replacement should also have a documented investment rationale, so that operational convenience does not become the only reason for the change.
Try it yourself
A redemption settles Friday, but the destination fund cannot accept the money until Tuesday. What needs explicit planning?
Show the worked answer
The interim cash holding, market exposure gap, dealing rules and responsibilities for completing and confirming the destination investment.
Further reading
Educational material, not a recommendation to buy or sell a fund. Numerical examples are hypothetical. This guide focuses on U.S. collective investment funds and retirement CITs. Terms, eligibility and tax treatment vary by fund, account and jurisdiction.


