

Structured Notes and Payoff Design · Hybrid Securities
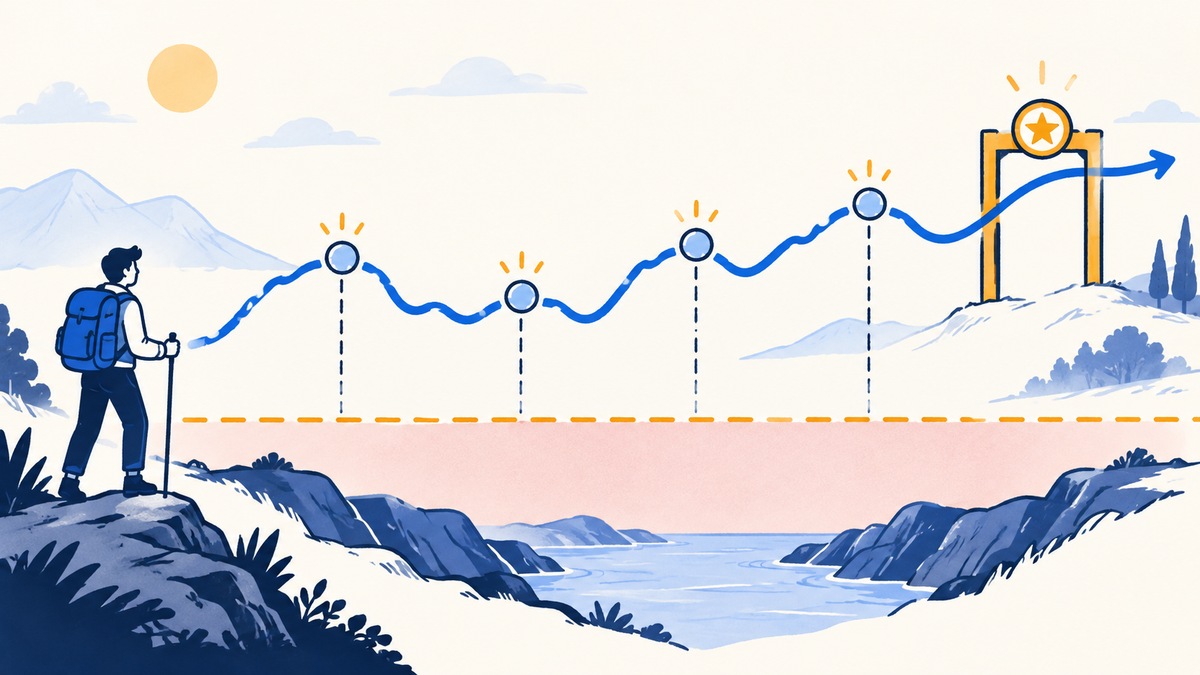
Autocalls and barriers make observation dates part of the payoff. Two investments with the same final asset price can have different outcomes when the earlier paths differ.
Separate each contractual test
An autocall can redeem a note early when a reference condition is met on a specified date. A coupon barrier can control whether a distribution is paid. A principal barrier can control downside repayment at maturity. These tests may use different levels and observation schedules. Combining them into one barrier number hides important differences.
Follow two illustrative paths
Assume a note is automatically redeemed for principal plus an agreed payment if the reference is at or above its initial level on an annual observation. Path A reaches 105% at that observation and the note ends. Path B reaches 95% and continues. Even if the reference later finishes at the same level in both hypothetical paths, the first investor no longer holds the note.
The first investor must reinvest the proceeds. The second remains exposed to subsequent reference moves and issuer credit. An advertised maximum annual coupon cannot be multiplied by the full original term if early redemption can stop future payments.
Distinguish barrier from buffer
Suppose a maturity barrier is 70% of the initial asset level and the contract exposes the investor to the full reference decline if it finishes below the barrier. A final level of 65% can result in a 35% principal loss, not merely a loss of the 5 percentage points below the barrier. A buffer structure can work differently. Read the actual loss formula.
Test paths around every threshold
Create examples just above and just below each barrier, plus an early call and an issuer failure case. For baskets, determine whether the worst performing component controls the result. Observation holidays, corporate actions and adjustment authority can matter. A real issuer filing is useful for learning the document structure, but its numbers and conditions belong only to that particular issue.
Try it yourself
A $1,000 note follows the hypothetical full decline barrier rule above. The reference ends at 60% of its initial level. What principal amount is returned if the issuer performs?
Show the worked answer
The reference has fallen 40%, so the principal payment is $600 under that assumed rule. Any coupon must be calculated separately.
Further reading
Educational material, not a recommendation to transact. All numerical examples are hypothetical and exclude costs unless stated. Actual terms, eligibility, tax treatment and broker procedures depend on the security and jurisdiction.


