Allocation and Ongoing Review · Hedge Funds
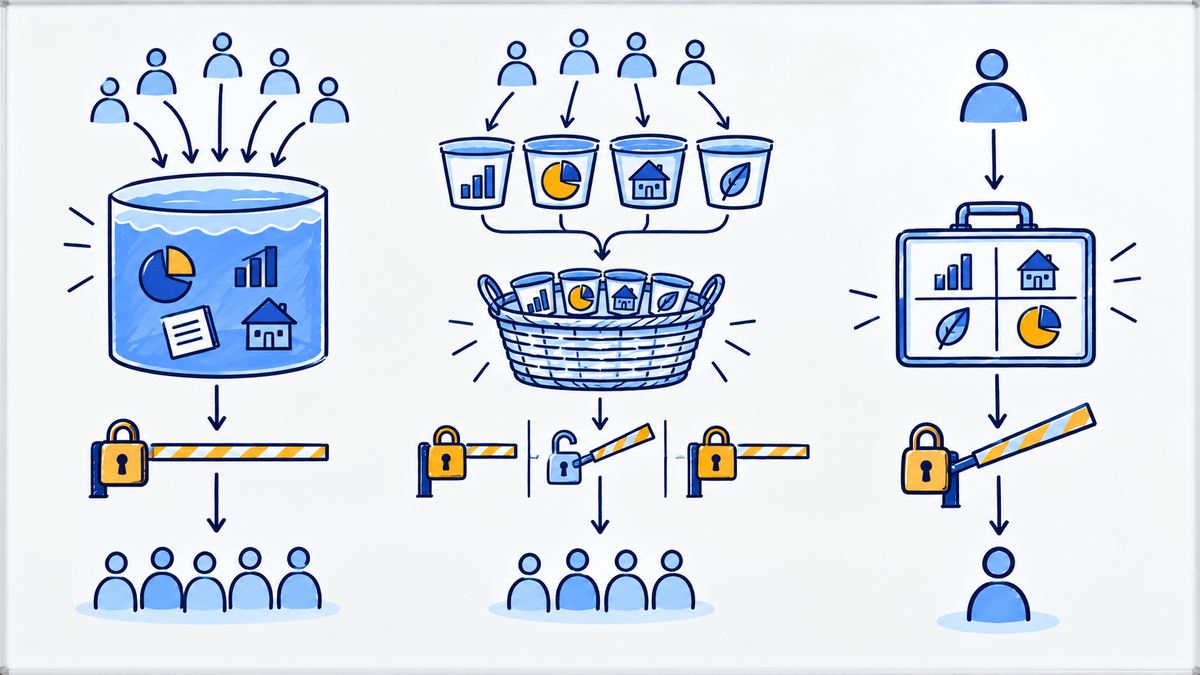
Investors can encounter hedge fund strategies through several structures. The wrapper changes fees, control, transparency and liquidity even when the underlying idea sounds similar.
Understand the additional layer
A fund of funds allocates to other funds. It can provide manager selection and monitoring, but may add its own fees and expenses above those charged by underlying managers. Its withdrawal promises must be assessed against the liquidity of those investments.
Diversification across manager names does not guarantee diversification across positions or risks. Ask for overlap analysis and the process used to identify shared financing, factor and liquidity exposures. Examine whether the allocator’s claimed advantage remains valuable after the extra cost.
Consider a managed account
A separately managed account can provide greater visibility and negotiated controls, depending on the agreement and infrastructure. It may also require more capital, administration and investor oversight. Ownership and control arrangements differ from buying an interest in a pooled fund.
Greater transparency does not automatically produce better decisions. The investor needs the resources to interpret positions, collateral and exceptions. Some strategies or instruments may be impractical in a particular account structure, so performance can differ from the manager’s flagship fund.
Compare public alternative wrappers carefully
An alternative mutual fund can offer access under public fund rules with different operating constraints from a private hedge fund. Similar strategy language does not establish identical holdings, leverage, fees or liquidity. Read the prospectus and actual portfolio disclosures.
For a simplified cost illustration, suppose $100 earns 8% after all underlying fund charges, then an allocator deducts a $1 fee based on starting capital. The investor retains $107 before other expenses and taxes. The extra layer reduces the result to 7% under these assumptions, but the value of its services still needs separate evaluation.
Try it yourself
Two access routes report the same strategy name. One has daily dealing and the other quarterly dealing with a lockup. What should be compared before assuming they are equivalent?
Show the worked answer
Compare actual holdings, leverage, permitted instruments, fees, cash buffers, execution and withdrawal conditions. The different liquidity promises may require different portfolio construction.
Further reading
Educational material, not a recommendation to buy or sell a fund. Numerical examples are hypothetical. Fund terms, investor eligibility and tax treatment vary by product, account and jurisdiction.