

Indices and Investment Strategies · ETFs
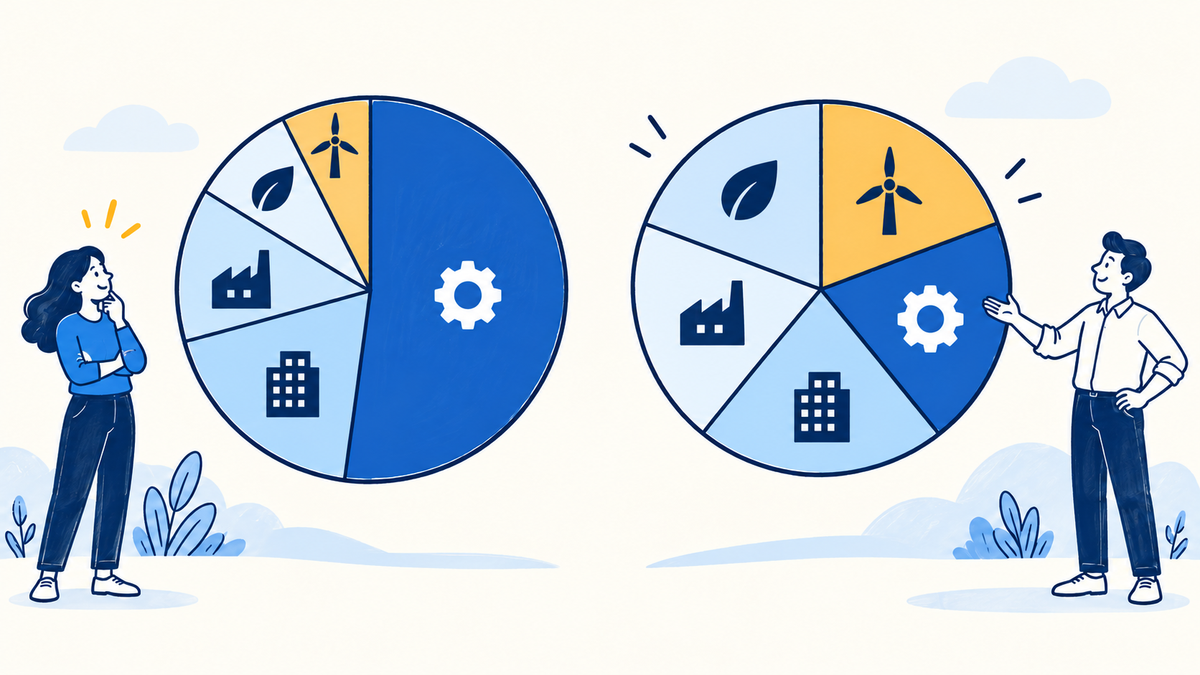
The same companies can form very different portfolios when their weights change. Compare concentration, turnover and the assumptions behind each method.
Market value determines the initial weights
A market capitalisation weighted index gives larger companies greater weight, often adjusting for shares available to public investors. Price changes naturally alter weights. It does not need to sell every winner simply because its price rose, although corporate actions and index reviews still require trades. Large company concentration can increase substantially over time.
Equal weights require maintenance
An equal weighted index starts each constituent at the same target allocation at a scheduled rebalance. Between rebalances, prices cause weights to drift. Restoring equality generally trims relative winners and adds to relative laggards. This can increase turnover and exposure to smaller companies compared with a market cap benchmark. It does not eliminate equity market risk.
Calculate the difference in exposure
Consider four firms worth $70 billion, $20 billion, $8 billion and $2 billion. Their simple market cap weights are 70%, 20%, 8% and 2%. Equal weighting starts them at 25% each. A $10,000 allocation therefore puts $7,000 versus $2,500 into the largest firm. The second portfolio is less dependent on that firm but much more exposed to the smallest one.
Judge the method against the intended role
Compare sectors, company sizes, turnover, liquidity and total costs rather than a recent performance winner. An equal weighted sector index can still be concentrated in one industry. A market cap index can be diversified across many markets yet dominated by a few businesses. Neither label substitutes for examining the actual portfolio and how it interacts with holdings you already own.
Try it yourself
An equal weighted fund has ten holdings at a rebalance. What is each target weight, and will it necessarily remain unchanged until the next rebalance?
Show the worked answer
Each starts at 10%. Prices and other portfolio events can change the weights between scheduled rebalances.
Further reading
Educational material, not a recommendation to transact. All numerical examples are hypothetical and exclude costs unless stated. Actual terms, eligibility, tax treatment and broker procedures depend on the security and jurisdiction.
Continue learning
- Previous lesson: Reading the rules behind an ETF benchmark
- Next lesson: Factor ETFs and the patience required for a tilt
- Explore all ETFs lessons


