

Fund Structures and Corporate Actions · Closed End Funds
Not every closed end structure trades like a listed income fund. Interval funds, tender offer funds and business development companies require additional distinctions.
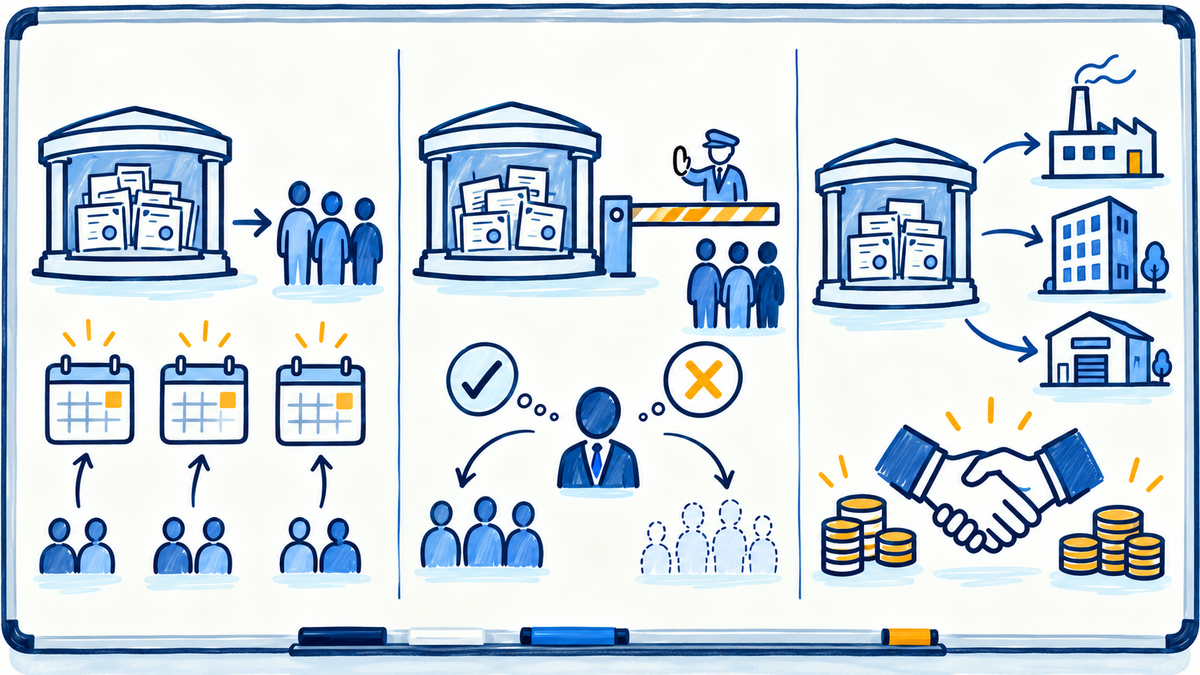
Interval funds use scheduled repurchases
Most interval funds do not trade on an exchange. They offer periodic repurchases of a limited portion of shares, commonly at intervals of three, six or twelve months under their terms. Investors may be unable to sell the full amount requested when offers are oversubscribed. Read the notice and pricing schedule because a request and its eventual valuation can occur at different times.
Tender offer funds have a different process
A tender offer fund may provide liquidity through discretionary tender offers rather than the interval structure’s specified repurchase framework. The frequency, size and conditions depend on the fund. A history of offers does not create an unconditional right to redeem whenever you want. Examine eligibility, sales charges and valuation practices.
BDCs focus on business financing
Business development companies generally invest in smaller or developing businesses through loans, equity or related instruments. Some are publicly traded and others are not. They have a distinct regulatory framework and financing risks. Credit quality, nonaccrual loans, valuation, funding and incentive fees deserve attention beyond the headline distribution.
A listed BDC’s market price can differ from its reported NAV. Private holdings can make valuation judgments particularly important. Read its periodic company reports and risk disclosures rather than assuming a standard bond fund analysis is sufficient.
Match the structure to the cash need
Suppose an investor needs $20,000 next month but owns shares in a fund with a future limited repurchase window. A published NAV of $20,000 does not guarantee access to that cash on the required date. Limited liquidity should be treated as a portfolio constraint before investing, not discovered during an emergency.
Try it yourself
An interval fund receives requests exceeding its repurchase offer. Is a published NAV enough to guarantee that all requested shares will be redeemed?
Show the worked answer
No. Repurchases may be prorated under the applicable terms. Confirm the offer size, timing, pricing date, fees and procedures before relying on the proceeds.
Further reading
- SEC Investor.gov: Interval funds
- SEC Investor.gov: Publicly traded business development companies
- Investment Company Institute: Fund structures and leverage
Educational material, not a recommendation to buy or sell a fund. Numerical examples are hypothetical. Fund terms, investor eligibility and tax treatment vary by product, account and jurisdiction.
Continue learning
- Previous lesson: Term funds and target term funds
- Next lesson: Giving closed end funds a role in a portfolio
- Explore all Closed End Funds lessons


